Annuities Are Not Just for Retirement Income
While they may be best known for providing guaranteed retirement income, annuities can also help you grow wealth, protect savings, and maximize Social Security benefits.
1. Earn more attractive returns.
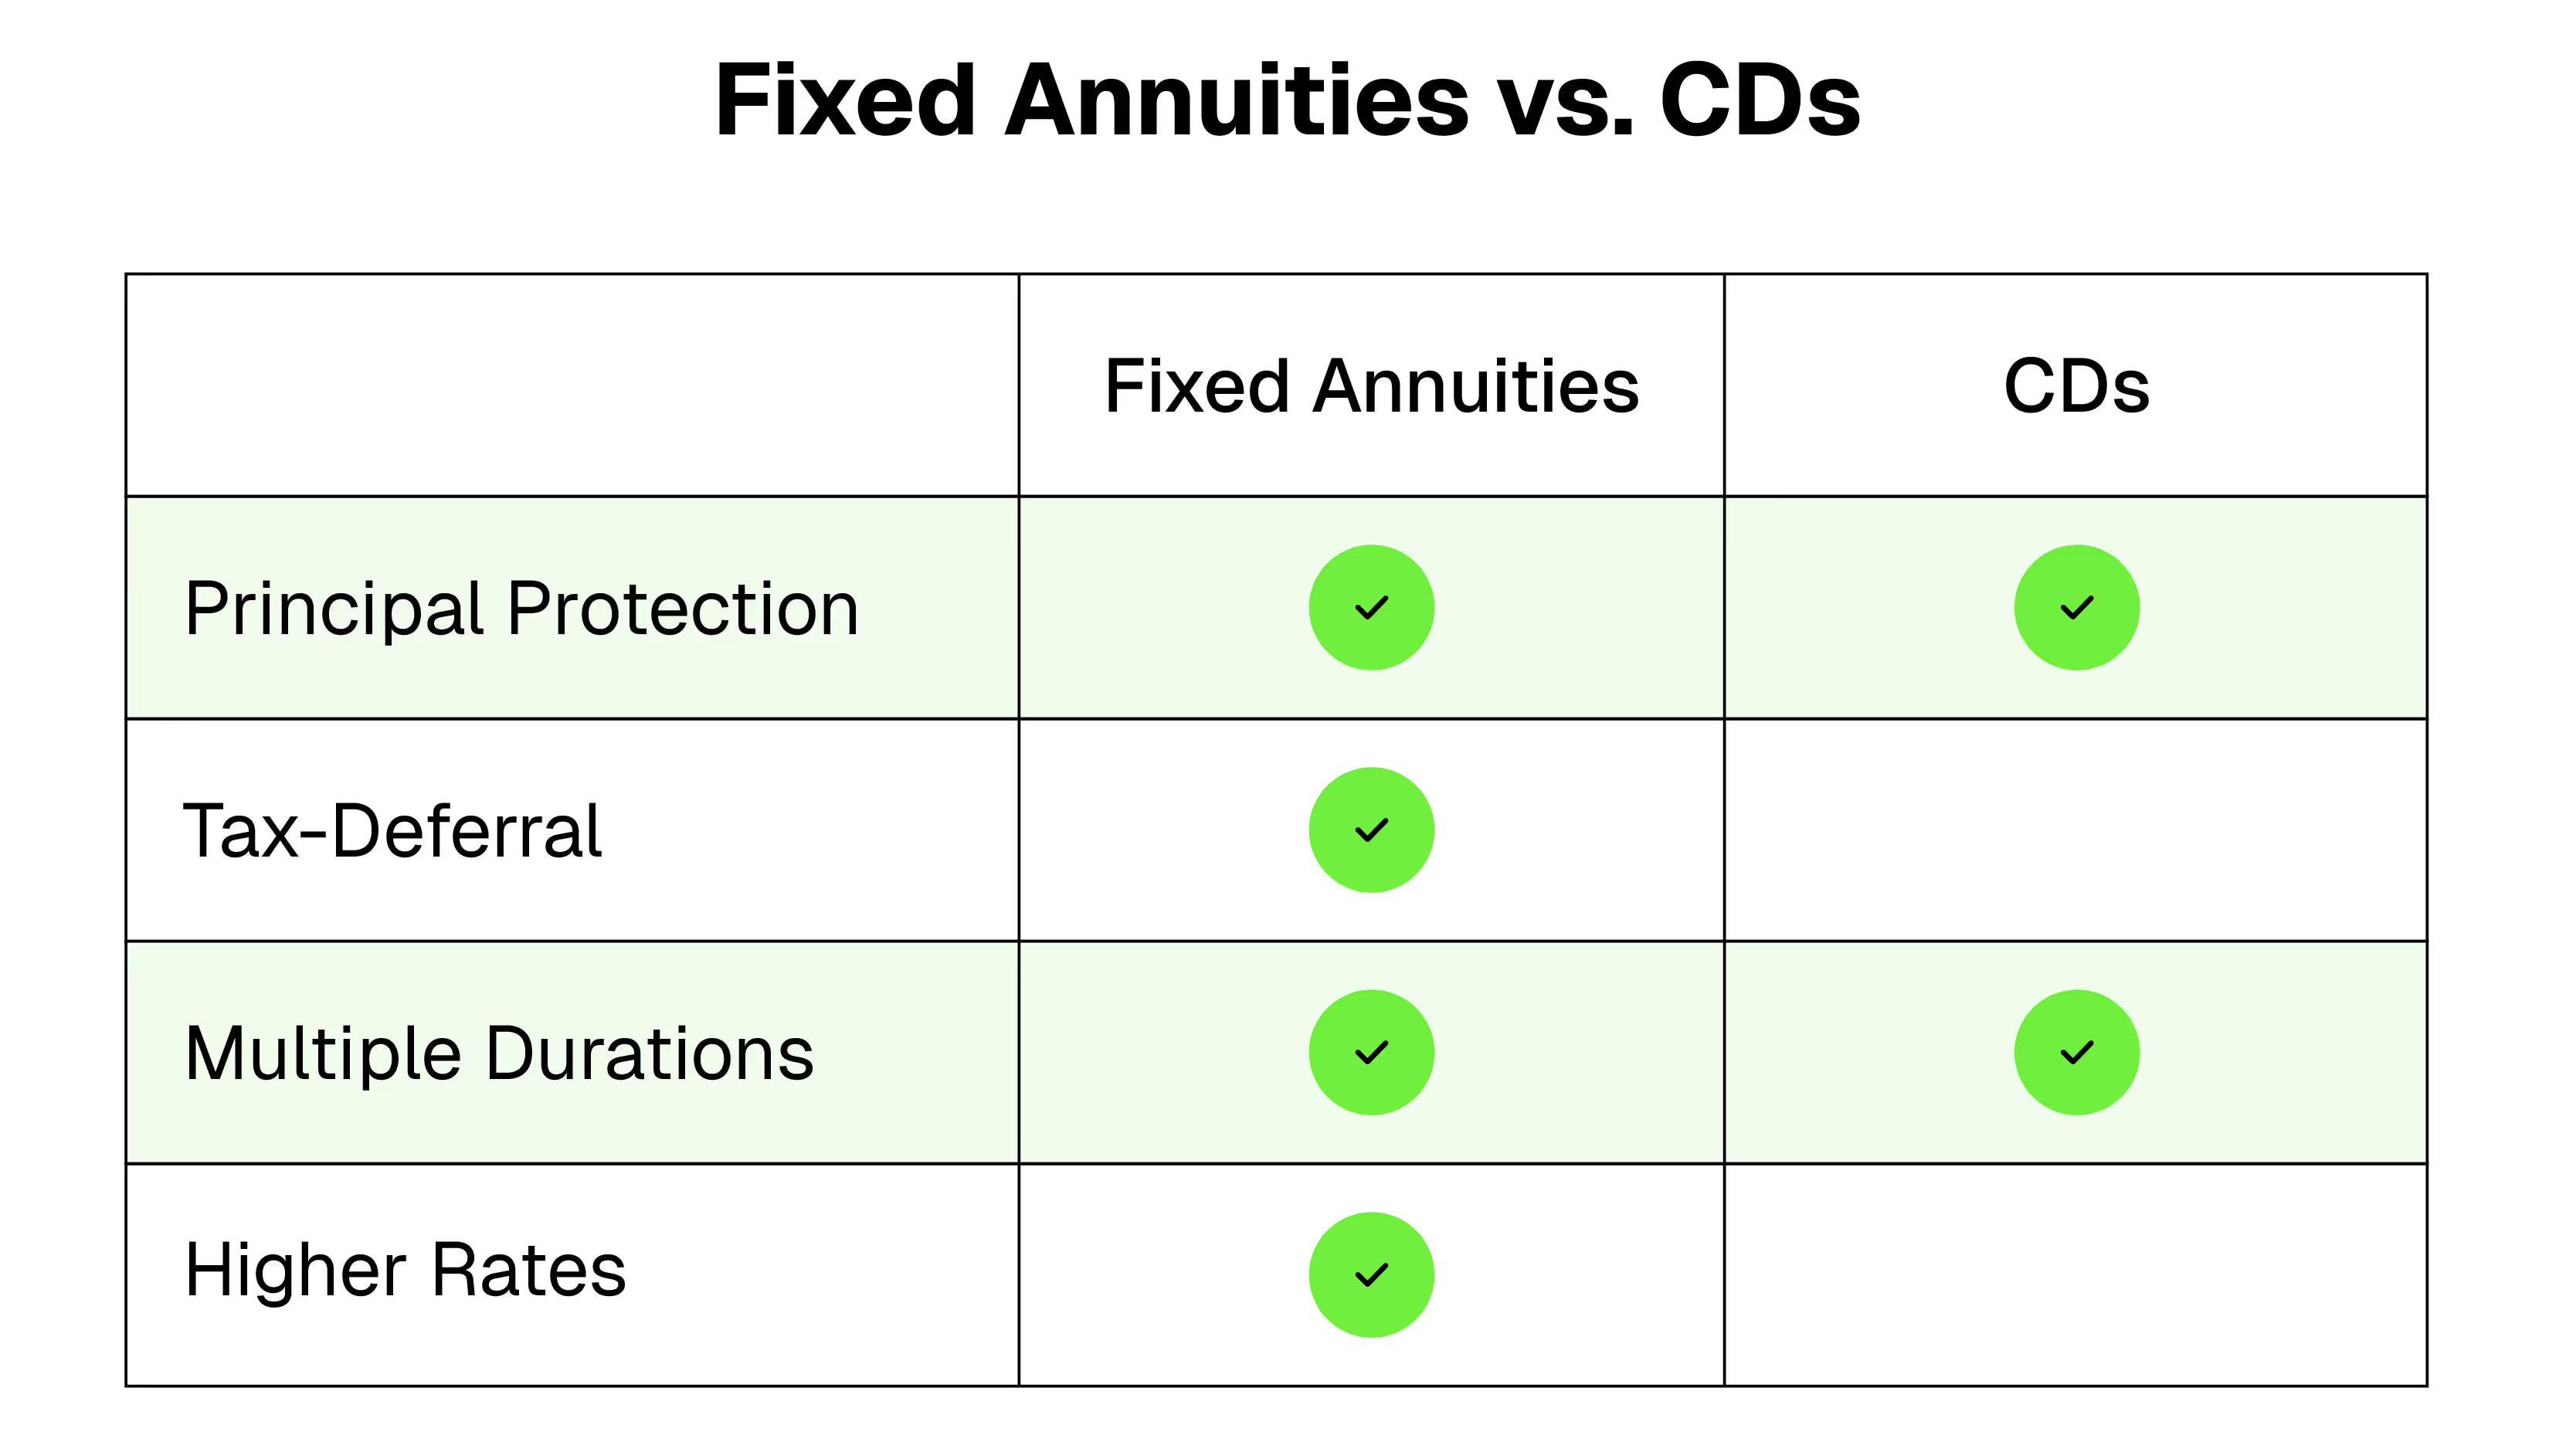
Interest rates remain higher than they have for much of the last decade. As a result, many types of conservative investments offer higher yields than they did just a few years ago. Commission-free multi-year guaranteed annuities (MYGAs) can be an attractive alternative to a short-term bond or a certificate of deposit (CD) because they offer similar features and, typically, a higher interest rate and more flexibility.
MYGAs are fixed annuity products issued by insurance companies. They offer a guaranteed rate of return over a specific period of time, which generally ranges from three to 10 years. MYGAs can help investors generate better returns and the interest grows tax deferred so it’s compounded, unlike most CDs.*
2. Protect savings in volatile markets.
Nobody wants to face a bear market — a drop of 20% or more — as retirement nears. Even a stock market correction, a drop of 10%, can mean working longer or having to spend less in retirement. But many investors also suffer from FOMO — fear of missing out — and don’t want to be out of the stock market entirely.
Registered Index-Linked Annuities (RILAs) help investors limit the extent of losses due to poor market returns while still participating in market upside.
For example, if a RILA contract has a 10% buffer over one year, the insurance company accepts the first 10% of any market loss. If the market falls by 20%, the annuity owner would see the account value drop by only 10%.
The protection on the downside creates a trade-off; return potential when the market goes up is determined by the size of the downside buffer but can still offer double digit return opportunities.
3. Grow wealth tax efficiently.
People with high incomes often look for opportunities to save in tax-advantaged accounts, like workplace retirement plans, IRAs, and health savings accounts. However, there usually are limits on how much can be set aside in tax-advantaged accounts. An option to consider if you’ve maxed out your IRA contributions, for example, is a commission-free annuity.
These solutions offer tax-deferred growth, so the assets can grow without being subject to taxes until a withdrawal is taken.
4. Create a bridge to Social Security.
The later you take Social Security benefits, the higher the amount you receive. In 20261, the top benefit for someone who retired at:
Age 62 was $2,969 a month
Age 66 and 10 months was $4,152 a month (full retirement age)
Age 70 was $5,181 a month
Since retirement could last for 30 years or more, maximizing the income received from Social Security can make a big difference. Commission-free annuities can help people who retire before full retirement age by providing income until they begin taking Social Security payments.
For example, an early retiree can roll over a portion of a retirement plan account, or another type of savings or investment account, into an annuity that will deliver income until they are ready to turn on their Social Security benefits.
Annuities can deliver powerful benefits before and during your retirement. They can help you:
- Earn more attractive returns
- Protect savings in volatile markets
- Grow wealth tax efficiently
- Create a bridge to Social Security
If you have questions about whether an annuity is right for you, contact your financial advisor or reach out to a DPL Consultant at 1-877-625-5544. We can help.
[press-a-contact-location]
Disclosures
[1] Social Security Administration. January 2026.
*Annuities are insurance products issued by insurance companies. Guarantees are subject to the claims-paying ability and financial strength of the issuing insurer. Product features, limitations, fees, surrender charges, and availability vary by contract and carrier.
Past performance is not indicative of future results. No investment strategy can guarantee profit, achieve its objectives, or protect against loss in all market conditions.
Bonds and annuities are different financial products with different risks, costs, liquidity features, guarantees, and tax treatment. Comparisons are intended solely to illustrate general concepts.
Multi-Year Guaranteed Annuities (MYGAs) are not FDIC insured and are not bank deposits.
Registered Index-Linked Annuities (RILAs) involve investment risk and may lose value. Buffers and floors provide limited protection and do not eliminate investment risk. Investors should carefully consider the product’s objectives, risks, charges, expenses, and limitations before investing.